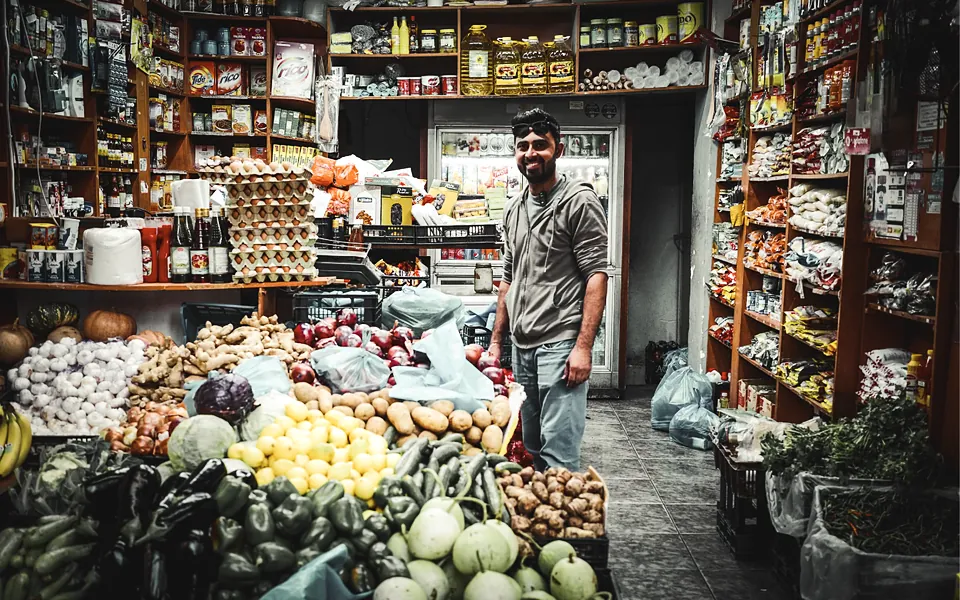
Convenience store guide
Convenience Store Financing: Inventory and Equipment Investments
Restocking never stops, coolers run around the clock and part of what flows through your account belongs to someone else. Here is how financing fits a convenience store, and why your product mix shapes the review.
Tell us what the funds are for and what your store sells so an advisor can review options that may fit.
 By Correia Financial
On this page
The short answer
Convenience stores usually finance two things: equipment such as coolers, freezers, shelving and point of sale systems, and inventory to keep shelves full through steady restock cycles and busy seasons. Equipment financing often fits the first; a business line of credit or short-term working capital may fit the second.
What you sell matters as much as how much you sell. Tobacco, vape, alcohol, lottery and fuel revenue can change which providers will review your store, and lottery ticket sales and collected taxes are not your revenue. Availability is provider dependent, so confirm it for your mix before you rely on any option.
Why your product mix matters before you apply
Two convenience stores with the same monthly deposits can get very different responses from financing providers. The difference is often what the store sells. Tobacco, vape, alcohol, lottery and fuel each come with licensing, regulation or money that belongs to someone else, and providers weigh those lines differently.
Whether a provider will review a store with these revenue lines is provider dependent. Some review them routinely, some limit how much of your revenue can come from a category, and some do not review certain categories at all. Policies change, so treat any general statement, including this one, as something to confirm for your store.
Tobacco and vape
Federal law bars sales to anyone under 21, and since September 30, 2024 retailers must check photo ID for buyers under 30. FDA has sought civil money penalties from retailers selling unauthorized e-cigarettes.
State tobacco licensing
In California, each location needs its own Cigarette and Tobacco Products Retailer’s License, renewed every year, and vapor products have been covered since January 1, 2017.
Lottery
Ticket sales may not be the store’s money. In Florida, for example, state law says lottery receipts are held in trust until delivered to the state.
Fuel
Underground tank owners must show they can pay for cleanup and third party damage from petroleum releases, which adds environmental questions to a review.
Alcohol
Sales require a state license. Ask how a provider treats the license if the store changes hands or the license is suspended.
SNAP
Authorization comes with staple food stocking standards, which USDA tightened in a final rule published May 7, 2026.
Before you apply, write down roughly what share of your sales comes from each of these categories. It is one of the first things that decides which providers can look at your store, and it saves time for everyone.
How stock cycles drive a convenience store’s cash needs
A convenience store restocks constantly. Beverages, snacks, tobacco and grocery items arrive from different distributors on different schedules, and many of them sell within days. Cash leaves for the next order before the last one has fully sold, so the store’s need is usually less about one big purchase and more about keeping the shelves and coolers full without draining the account.
- OrderYou order from each distributor based on recent sell-through.
- Delivery and invoicePayment is due on terms each distributor sets.
- SalesFast movers sell within days; slower items sit longer.
- SettlementCard sales settle into your account on the processor’s schedule.
- ReorderThe next order is placed, often before slower stock has sold.
A general illustration. Distributor terms and settlement timing vary.
Not every category turns at the same speed. Tobacco ties up a lot of cash per carton, beverages swing with the weather and seasons, and grocery items may sit longer. A business line of credit suits that pattern when it rises before a busy stretch and comes back down as stock sells. A balance that never comes down suggests the line is covering a gap that inventory does not repay.
New SNAP stocking standards add to the shelf
If your store accepts SNAP, the stocking rules shape part of your inventory. USDA’s current eligibility page describes Criterion A as at least 36 staple food items: three varieties in each of four staple food categories, three stocking units of each, and a perishable variety in two of the categories.
USDA’s final rule published May 7, 2026 says authorized retailers must carry seven varieties of items across four categories of staple foods (protein, grains, dairy, and fruits and vegetables), with the updates going into effect in fall 2026. For a small store, more varieties can mean more cooler space and more perishable stock to manage. Check the final rule and USDA’s guidance for the exact requirements and dates that apply to you.
Lottery, taxes and other money that passes through your account
Convenience store bank statements often show deposits that are not the store’s income. Lottery ticket sales, sales tax and excise taxes collected at the register all pass through the account on their way to someone else. A provider reading your statements may try to separate what you keep from what you owe.
Lottery is the clearest case. In Florida, for example, state law says money retailers receive from selling lottery tickets is held in trust before delivery to the state lottery department, and the department may require retailers to set up separate electronic funds transfer accounts. Rules differ by state, so check yours, but in general the commission is your revenue and the ticket sales are not.
| Deposit or flow | Is it the store’s revenue? | How to present it |
|---|---|---|
| Merchandise sales | Yes | Show it by category if you can, so tobacco, vape and alcohol shares are clear. |
| Lottery ticket sales and sweeps | Generally no; your commission is | Point out the sweeps on your statements and show commission income separately. |
| Sales and excise taxes collected | No, it is owed to the government | Show that filings and payments are current. |
| Fuel sales | Yes, but the store keeps only the margin | Separate fuel from in-store sales and show the fuel margin. |
| Transfers between your own accounts | No | Label them so they are not counted twice. |
Presenting your deposits this way helps a provider judge what payment the store can actually support. For more on separating sales from other deposits, see what counts as business revenue in a financing application.
What providers may review, and how to prepare
There is no universal standard for convenience store financing. Each provider sets its own criteria, and the questions follow the product mix described above. Preparing in this order keeps the review focused.
- 1
Break down your revenue
Estimate the share of sales from tobacco and vape, alcohol, lottery, fuel and everything else, using your point of sale reports.
- 2
Gather licenses and authorizations
Have your tobacco retailer license, alcohol license, lottery contract and SNAP authorization ready, plus tank compliance records if you sell fuel.
- 3
Pull your bank statements
Correia Financial’s initial review uses your last four complete months of business bank statements. Mark lottery sweeps, tax payments and transfers so they are easy to follow.
- 4
Define the use of funds
For equipment, get vendor quotes that include delivery and installation. For inventory, show what you are buying and how fast it sells.
- 5
List what you already owe
Include existing loans, equipment agreements and any advances, with their payment amounts and frequency.
Providers may also ask for a profit and loss statement, business tax returns, your lease and, for larger requests, a balance sheet. Our guide to business loan requirements explains each document.
Financing coolers, freezers, shelving and point of sale systems
Coolers and freezers run around the clock, and when one fails, the stock inside is at risk. Refrigeration, shelving, point of sale systems, security cameras and food service equipment are the long-lived purchases a convenience store is most likely to finance.
Equipment financing lets the cooler or case itself serve as collateral, so payments can run over a period closer to how long the unit will last. Some offers are leases rather than loans, and a lease ends differently: depending on the contract, you may hand the equipment back, extend the lease or buy it out. Find out which you have, and whether the provider’s UCC filing will cover only the equipment or reach other business assets.
Hypothetical example: replacing reach-in coolers
A store needs to replace four aging reach-in coolers. The vendor quote is $36,000, including delivery, installation and removal of the old units.
Paying cash would cut the store’s reserve to a level that would not cover a slow month. Instead, the owner compares an equipment financing offer with fixed monthly payments against the store’s monthly profit after all other expenses, including the existing card processing and rent.
The owner also asks the provider for the total repayment, any fees, the estimated APR, whether there is a down payment and what happens if the store pays the balance early, and counts the repair bills on the old coolers, which should stop once the new units are installed.
Hypothetical, with round numbers chosen for illustration. It is not a quote or an offer, and real terms depend on the provider, the equipment and your store.
If the down payment, installation or electrical work is more than you expected, read how to plan the full cost of an equipment purchase.
If you sell fuel: what changes in a review
Fuel adds a large volume of deposits, but the store keeps only the margin after the cost of the fuel and card fees. It also brings environmental obligations that most retailers do not have, which is why some providers treat stores with fuel differently.
Under EPA rules, owners and operators of regulated petroleum underground storage tanks must demonstrate financial responsibility, which EPA describes as making sure money will be available to clean up releases and to pay for property damage or bodily injury they cause. For tanks at petroleum marketing facilities, the required amount is $1 million per occurrence, with an annual aggregate of $1 million for owners of 1 to 100 tanks.
Owners can meet the requirement through a qualifying state fund, insurance, self-insurance, a corporate guarantee, a letter of credit or a surety bond. A provider reviewing a fuel station may ask how you meet it, whether there have been releases and who owns the tanks. Tank replacement, canopies and dispensers are specialized projects, and not every equipment provider reviews them. Ask about this early.
Comparing costs and payment schedules
Convenience stores often take in cash every day, which can make daily or weekly payments look manageable. Compare offers on the full picture instead: funds disbursed after any fees, total repayment, total cost, payment amount and frequency, estimated APR where one is provided, any UCC filing or lien, and whether a personal guarantee is required.
With revenue based financing, a provider purchases part of your future sales instead of lending to you, so no interest rate applies. Remittances may be a percentage of sales or a set amount collected daily or weekly. Make sure you know whether the percentage applies to all deposits, including lottery and fuel, because pass-through money can make a sales-based remittance larger than your margin can support.
A line of credit or a term loan charges interest. With a line, you pay interest on what you draw, and some lines add draw or maintenance fees. See how daily, weekly and monthly payments compare before you choose a schedule.
When to hold off on financing
Financing works best when it pays for something that brings the cash back: equipment that keeps stock sellable, or inventory with a proven sell-through. It is a poor fit for covering losses that come from shrinkage, theft, slow-moving stock or a category that is shrinking.
It is also worth pausing if a regulatory change could cut into a major revenue line, such as a local restriction on flavored tobacco or a change to your lottery or alcohol license. Borrowing against revenue that may not be there next year can leave you with payments and less income to cover them. Settle the uncertainty first, or size the request to the part of the business that is not at risk.
If you already carry an advance or loan, a new payment stacks on top of it; see what providers consider when you already have financing.
Frequently asked questions
Will providers finance a convenience store that sells tobacco or vape products?
Some do and some do not; it is provider dependent and policies change. A provider may also look at what share of sales comes from these products and whether licenses are current. Share your product mix early so an advisor can tell you which providers may review your store.
Do lottery sales count as revenue in a financing review?
Generally, the ticket sales themselves are not your revenue, because the money is owed to the state lottery. In Florida, for example, state law says retailers hold lottery receipts in trust until delivered. Your commission is revenue, so show it separately and point out the lottery sweeps on your statements.
Can I finance new coolers or freezers?
Coolers and freezers can often be financed with the equipment as collateral, through equipment financing or a lease. Price the whole job, including delivery, installation and hauling away old units, and ask each provider for its total repayment and fees.
Does selling fuel make financing harder?
It can change the review. Fuel adds large deposits with a smaller margin, and owners of underground petroleum tanks must meet EPA financial responsibility requirements for cleanup and third party damage. Some providers do not review fuel stations or tank projects, so ask early.
How do the new SNAP stocking rules affect my inventory?
USDA’s final rule published May 7, 2026 says authorized retailers must carry seven varieties of items across four categories of staple foods, with the updates going into effect in fall 2026. That can mean more varieties, more perishable stock and more cooler space. Check USDA’s guidance for your exact requirements.
Is revenue based financing a good idea for a convenience store?
Possibly, for a short and specific need. Because the provider is buying part of your future sales, ask exactly which deposits its remittance is based on. If lottery or fuel money is included, the remittance can take more than your margin supports.
Is Correia Financial the lender?
No. Correia Financial is a brokerage, not a lender. It looks at your store’s profile and works with third party providers, and each provider decides whether to offer financing and on what terms.
Sources
- Store Eligibility RequirementsU.S. Department of Agriculture
- USDA Requires SNAP Authorized Retailers to Carry More Real FoodU.S. Department of Agriculture
- Tobacco 21U.S. Food and Drug Administration
- FDA Seeks Civil Money Penalties Against 11 Retailers Selling Unauthorized E-CigarettesU.S. Food and Drug Administration
- Cigarette and Tobacco Products Licensing Registration and Renewal InformationCalifornia Department of Tax and Fee Administration
- Florida Statutes § 24.114: Bank deposits and control of lottery transactionsThe Florida Senate
- 40 CFR 280.93: Amount and scope of required financial responsibilityElectronic Code of Federal Regulations
- UST Financial ResponsibilityU.S. Environmental Protection Agency
Sources reviewed October 12, 2026.