
Cleaning industry guide
Cleaning Business Financing: Expanding Into Commercial Contracts
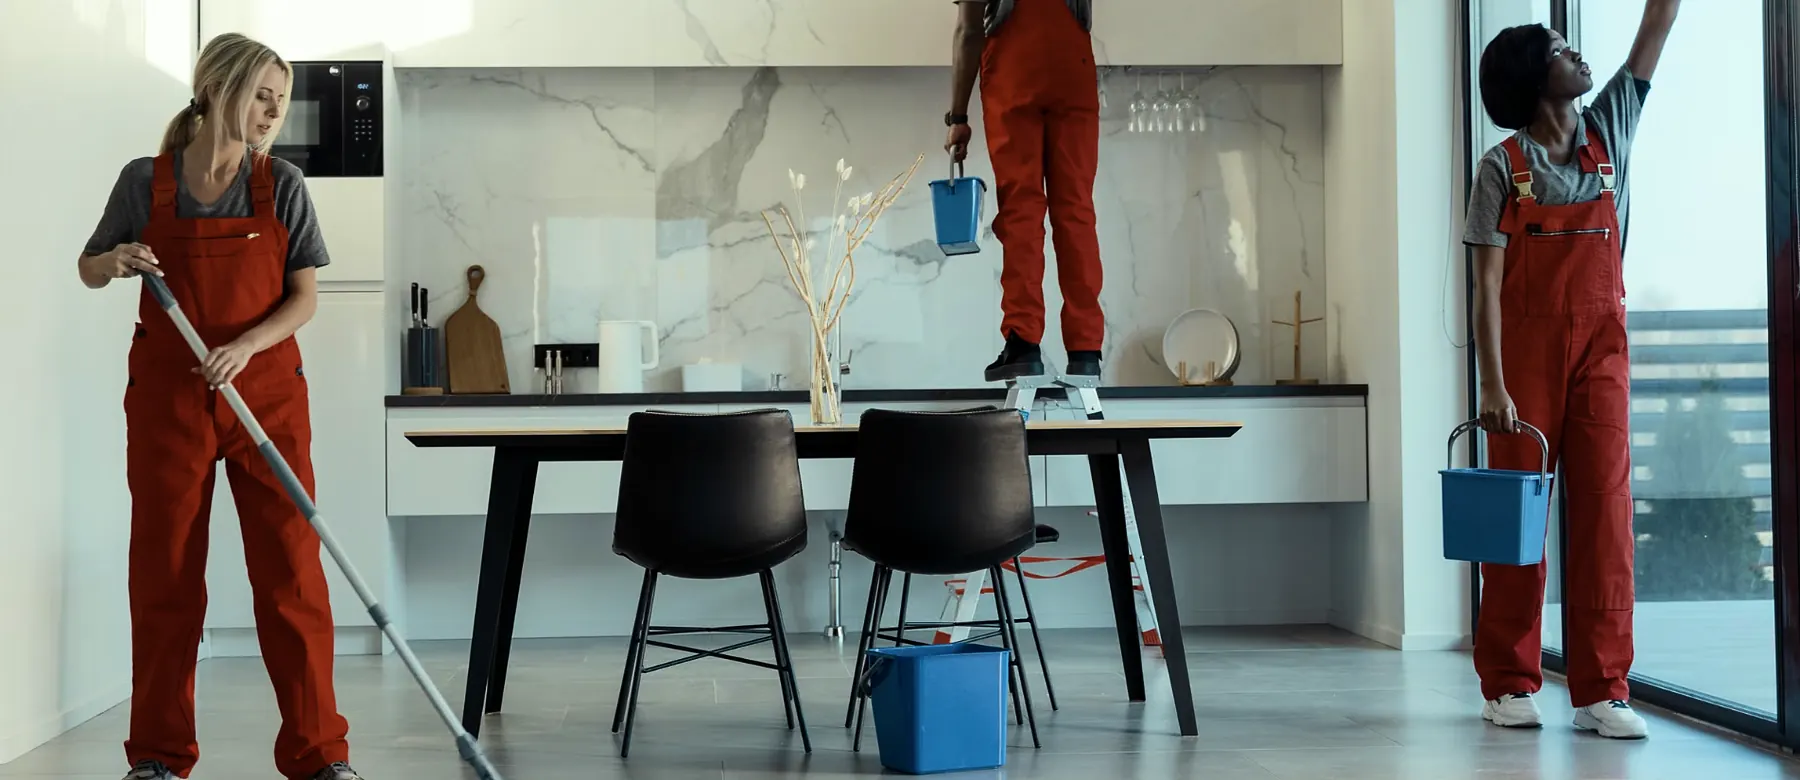
The short answer
The main financing need in commercial cleaning is the gap between paying staff and collecting from clients. Invoice factoring often fits when the businesses you bill are established and pay reliably but slowly. A business line of credit often fits when the gap repeats with each new account. A short working capital product can cover a one time startup cost when the repayment source is clear.
Size the gap before you choose: count the paydays and supply costs between signing a contract and receiving its first payment. Providers make every credit decision and set the terms, and eligibility can depend on the clients you bill as much as on your business.
Tell us about the contracts you are adding so an advisor can review which structures providers may offer.
 By Correia Financial
On this page
Why a new commercial account strains cash before it pays
Commercial cleaning contracts are attractive because they repeat: the same buildings, the same scope and a predictable monthly bill. The catch is timing. You hire, train and supply a new account before the first night of service, your staff are paid every payday from the start, and the client pays each invoice on its own terms after the work is done.
Staffing makes the gap larger than it looks. According to the U.S. Bureau of Labor Statistics, many janitors and building cleaners work evening hours because offices are cleaned while they are empty, and while most work full time, part-time work is common. A single office contract can add several people to payroll at once.
- Contract signedScope, schedule and invoice terms are set.
- Staff hiredRecruiting and training hours come before service.
- Site suppliedChemicals, consumables and machines for the building.
- Service and payrollCrews clean nightly and are paid every payday.
- Invoice sentOn the contract’s billing schedule, often monthly.
- Client paysOn the client’s terms, after any approval steps.
A general illustration. Billing and payment terms vary by contract and client.
How large the gap gets: a hypothetical first contract
The gap is easier to plan for once you put dates on it. The example below follows one new office account from signing to first payment.
Hypothetical example: a five night office contract
A cleaning company wins a five night a week office contract billed at $24,000 a month, with each invoice due 45 days after the end of the service month. Serving it takes eight part-time cleaners and a supervisor, with payroll of about $7,000 every two weeks including payroll taxes.
Before the first night, the company spends $4,000 on supplies and $6,000 on a floor scrubber and vacuums. The first invoice goes out on day 30 and is due on day 75. By then the company has met five payrolls, about $35,000, on top of the $10,000 startup spend: roughly $45,000 out before the first $24,000 comes in.
From the third month, a payment arrives every month and the account can carry itself, provided the price covers labor, supplies and overhead. The financing need is the startup gap, not the ongoing cost of the contract.
Round, hypothetical numbers for illustration, not a quote or an offer. Your wages, payment terms and costs will differ.
The same gap opens again with every new account, and it grows if clients pay later than their terms. That repeating pattern is why the structure you choose matters as much as the amount.
Factoring, a credit line or working capital: which fits the gap?
Three structures are commonly used to carry a cleaning company from first shift to first payment. They differ in who the provider is really underwriting, your business or the clients who owe you, and in whether you make payments at all. Select one to compare.
Invoice factoring
You sell invoices owed by commercial clients to a factoring company, which advances part of their value now and pays the rest, less its fees, when the client pays. It is a sale of receivables, not a loan, so there is no loan payment to make.
- Often fits when
- Clients are established businesses or institutions that pay reliably but slowly.
- What the provider weighs
- How reliably each client pays, often as much as your own credit.
- Cost to compare
- Discount and other fees, which can grow the longer an invoice stays unpaid.
- Watch for
- Client notification, recourse if a client does not pay, minimum volumes and agreement length.
Business line of credit
A provider approves a limit. You draw for payroll and supplies when a new account starts and repay as the client pays. A line is a loan, and interest generally applies only to what you have drawn.
- Often fits when
- A gap repeats each time you add an account, and collections reliably follow.
- What the provider weighs
- Your own cash flow, credit, existing debt and time in operation.
- Cost to compare
- Interest on the drawn balance plus any draw, maintenance or unused line fees.
- Watch for
- A balance that never falls, variable rates and reviews that can reduce the limit.
Working capital
Either a short-term working capital loan or revenue based financing, in which a provider buys a share of your future sales or receivables. Revenue based financing is not a loan and carries no interest rate, but it has a total cost you can compare.
- Often fits when
- The need is one time and the source of repayment is clear.
- What the provider weighs
- Recent deposits and how much revenue other payments already claim.
- Cost to compare
- Total repayment against the funds you receive, and the estimated APR.
- Watch for
- Daily or weekly payments that begin before the new account has paid you.
These are general patterns. Providers set their own criteria, some restrict certain industries or client types, and terms vary. For a deeper comparison of the first two, read receivables funding compared with a credit line.
How factoring works with commercial cleaning clients
Factoring turns invoices for work you have already performed into cash. Future months of a contract are not yet receivables, so factoring helps from the first invoice onward, not before it.
- 1
Complete the work and invoice
You clean for the service period and bill the client under the contract.
- 2
Submit and verify
The factor reviews the invoice and may confirm it with your client before advancing funds.
- 3
Receive the advance
You receive part of the invoice value now. The agreement sets the advance and any reserve held back.
- 4
Client pays the factor
After notice of the assignment, your client pays the factor instead of you.
- 5
Reserve released, less fees
When the client pays, the factor releases the reserve minus its fees under the agreement.
What notification means for your client relationships
Article 9 of the Uniform Commercial Code covers sales of accounts, which is what factoring is. Once a client receives notice that an invoice has been assigned, it can discharge the debt only by paying the factor, and it may ask for reasonable proof of the assignment. Expect property managers and facilities departments to see the change on their payables side.
Some client agreements say receivables may not be assigned. Under UCC Article 9, such terms are generally ineffective to stop the assignment of an account, with some exceptions, so ask the provider how it handles your contracts rather than assuming either way.
Which invoices a factor may accept
Factors look closely at who owes the invoice. Invoices to established commercial clients with clean payment histories are the usual candidates. Disputed invoices, credits for missed cleanings and heavy reliance on one client can reduce what is eligible; see how customer concentration affects factoring. Residential clients who pay at the time of service do not create receivables at all.
Government buildings follow separate assignment rules, covered in factoring government contract invoices. If you only need to sell some invoices, read spot factoring compared with whole ledger factoring.
Payroll, payroll taxes and supplies: the costs that cannot wait
Payroll is the largest and least flexible cost in a cleaning company. Staff are paid on your regular paydays whether or not a client has paid, and payroll taxes follow on their own schedule. The IRS requires employers to deposit federal income tax withheld and both the employer and employee shares of Social Security and Medicare taxes on a monthly or semiweekly schedule, by electronic funds transfer.
That is why the timing of financing matters. A line drawn or an invoice factored before payday keeps wages and tax deposits current; money that arrives after payday does not.
Supplies are smaller but constant: chemicals, liners, paper goods and replacement pads for every site. Machines are different. The Bureau of Labor Statistics lists floor buffers and vacuums among the tools cleaners use, and larger machines such as ride-on scrubbers are durable assets. A machine you will run for years is usually better matched to equipment financing than to a line you need for payroll.
Financing the startup gap only makes sense if the contract price covers labor at the hours the scope really takes. If a bid was priced too low, borrowing to carry it adds cost to a loss.
What providers may ask a cleaning company
Requirements depend on the provider and the product. Factoring reviews lean on the clients who owe you; lines and working capital lean on your own cash flow. Either way, expect questions like these.
About the clients you bill
- Who are your largest commercial clients, and what share of revenue does each provide?
- What invoice terms do they have, and how long do they actually take to pay?
- Are any invoices disputed, past due or reduced by credits for missed service?
- How long do your contracts run, and how much notice does a client need to cancel?
About your business
- How have your bank deposits moved over recent months?
- How much payroll will the new contract add, and when does it start?
- What financing, advances or tax obligations are you already paying?
- Who owns the business, and will an owner guarantee be requested?
Useful documents include recent business bank statements (Correia Financial’s application asks for the last four complete months), an accounts receivable aging, a client list, sample contracts and invoices, and payroll reports. Larger requests may add tax returns and financial statements.
How to compare what each option costs
Each product states its cost differently, so compare the funds you receive, the total you pay, any fees and the estimated APR side by side. In California, covered providers must give standardized disclosures, and the format differs by product.
Factoring
A California factoring disclosure shows the funding provided, an estimated APR, the finance charge, an estimated term and any costs to repurchase an invoice. The payment row reads not applicable, because you are selling the invoice rather than borrowing. The estimated APR rests on an assumption, for example that the client pays on the due date, so a client that pays late can make the real cost higher than the estimate.
Hypothetical example: factoring one month’s invoice
Using the $24,000 invoice above, suppose a factor advances $20,000 when the invoice is approved and holds $4,000 in reserve. The client pays 45 days after the invoice date and the factor’s fees come to $720, so the company receives the $3,280 balance of the reserve.
Total received: $23,280 for a $24,000 invoice, with $20,000 of it about six weeks sooner. If the client pays late and the fees run by time, the cost rises.
Hypothetical figures for illustration only. Advance amounts, reserves and fee schedules are set by each provider and agreement.
A line of credit and working capital
For a line, the California disclosure shows the APR, an estimated finance charge, estimated total payments and the draw period, assuming the full limit is drawn. For revenue based financing, the sales based financing disclosure shows an estimated APR, finance charge, estimated total payment, estimated payment and an estimated term built on assumptions about your revenue. Read how to compare working capital costs before you sign either.
When financing will not fix a cleaning company’s cash gap
Financing bridges timing. It cannot fix pricing, and it can make a weak contract more expensive.
Hold off or change the plan if a contract only works at fewer labor hours than the building really needs, if one client would supply most of your revenue and could cancel on short notice, or if clients routinely pay well past their terms. In those cases the cost of factoring rises, a line balance stays high and the risk sits with you.
Sometimes a better contract fixes the gap without financing. Ask whether a client will accept billing at the start of each month, a shorter payment term or a mobilization payment for a large start. Phasing in new buildings one at a time can also keep the gap within your reserves.
Frequently asked questions
Can a cleaning company factor its invoices?
Often, when the invoices are owed by commercial clients for work already performed and those clients have a reliable payment record. Residential clients who pay at the time of service do not create invoices to factor. Eligibility depends on the provider and on the businesses you bill.
Will my commercial clients know I am factoring?
They may. If the agreement calls for notifying clients, each one is told to pay the factor, and after that notice the Uniform Commercial Code allows the client to discharge the invoice only by paying the factor. Ask how and when clients will be notified before you sign.
Is a line of credit or factoring better for payroll?
It depends on what the provider is underwriting and on who owes you. A line is a loan based mainly on your own finances, and you repay what you draw with interest. Factoring is a sale of invoices based heavily on the credit of the clients you bill, with fees instead of payments. Compare total cost and how each fits your billing cycle.
Can I get financing before a new contract starts?
Factoring needs invoices for completed work, so it starts with your first bill. A line of credit or a working capital product may cover startup costs earlier, based on your existing revenue. Whether a provider weighs the new contract depends on the provider.
Does relying on one large client make financing harder?
It can. A factor may limit how much of your receivables can come from one client, and any provider will consider what happens if that client cancels. Spreading revenue across several contracts usually makes a request easier to support.
What happens if a client pays later than its terms?
With factoring, time-based fees can rise and, under a recourse agreement, you may have to buy back an invoice that stays unpaid. With a line, the balance stays high longer and interest accrues. Plan around how clients actually pay, not the terms printed on the invoice.
Does Correia Financial provide the financing?
No. Correia Financial is a brokerage that reviews your business and explores options with third party providers. The providers make all credit decisions and set every term, and applying is not a promise of approval or funding.
Sources
- Janitors and Building Cleaners, Occupational Outlook HandbookU.S. Bureau of Labor Statistics
- Depositing and reporting employment taxesInternal Revenue Service
- UCC Article 9, Section 109: ScopeLegal Information Institute, Cornell Law School
- UCC Article 9, Section 406: Discharge of Account Debtor, Notification of Assignment and Restrictions on AssignmentLegal Information Institute, Cornell Law School
- Cal. Code Regs. tit. 10, § 912: Factoring Disclosure Formatting and ContentsLegal Information Institute, Cornell Law School
- Cal. Code Regs. tit. 10, § 911: Commercial Open-End Credit Plan Disclosure Formatting and ContentsLegal Information Institute, Cornell Law School
- Cal. Code Regs. tit. 10, § 914: Sales-Based Financing Disclosure Formatting and ContentsLegal Information Institute, Cornell Law School
Sources reviewed October 12, 2026.
Related reading
 Industry Guides
Staffing agency financing: making payroll before clients pay